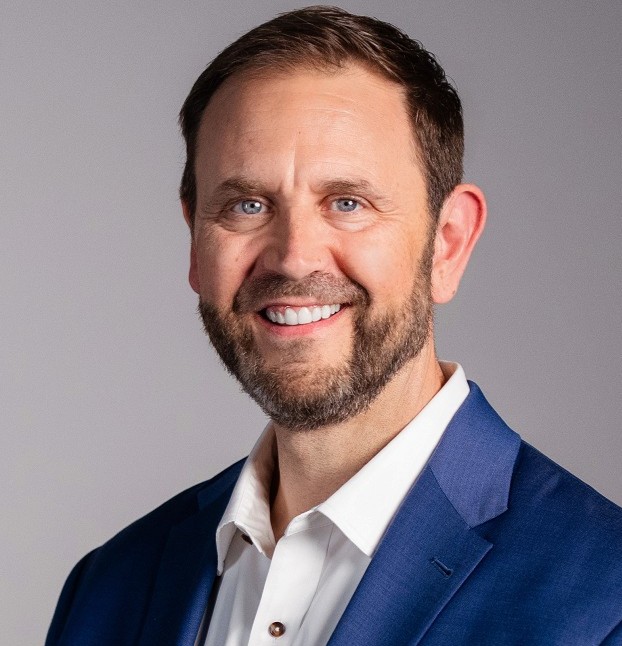
Charitable giving can take many forms, from annual gifts that support today's students to plans that create a lasting legacy for future generations. To help demystify some of the options available to donors, we spoke with Owen Malcolm (97C), managing director and wealth advisor with Apollon Wealth Management and a member of Berry's Planned Giving Council.
Owen offers practical guidance for alumni at every
stage of life,
beginning with foundational financial habits and moving into donor-advised funds, qualified charitable
distributions and
other tax-efficient ways to give.
What is one piece of charitable giving advice that surprises people?
One
phrase often used among financial planners is, "Friends don't let friends give cash."
That
doesn't mean cash gifts are bad. Instead, it's a reminder that there are often more
tax-efficient assets available to give. Appreciated stocks, mutual funds and
other investments can sometimes allow donors to support causes they care about
while potentially avoiding capital gains taxes and receiving a charitable
deduction.
For
many donors, giving appreciated assets can be one of the smartest ways to
maximize both their charitable impact and their tax benefits.
For alumni who are beginning their careers, what can they do now to prepare for future charitable giving?
Think beyond saving exclusively in a workplace retirement account. A
401(k) or 403(b) is an important part of a long-term financial plan, but most
withdrawals from traditional retirement accounts will eventually be taxable.
Young alumni can consider building a diversified financial portfolio that
may include a Roth IRA and an after-tax investment account. An after-tax
account does not have the same withdrawal restrictions as a retirement account
and may eventually contain appreciated investments that can be donated directly
to Berry or contributed through a donor-advised fund. Donating an appreciated
investment rather than selling it first may allow the donor to avoid capital
gains taxes associated with the asset.
What if someone wants to begin creating a legacy but isn't sure where to start?
Start with the assets you already have.
For someone age 70½ or older, a qualified charitable distribution from an
IRA can be a straightforward place to begin, and the first gift does not have
to be large.
Another option is to review your investment portfolio for stocks or other
assets that have increased significantly in value. Those assets may be strong
candidates for a direct gift to Berry or a contribution to a donor-advised fund
because of the potential tax deduction and capital gains benefits.
The most important thing is to find a giving strategy that aligns with
your financial situation, values and philanthropic goals.
Many people have heard terms like donor-advised fund and qualified charitable distribution but aren't sure what they are. Can you explain the basics?
A qualified charitable distribution, or QCD, is a withdrawal from an
individual retirement account that goes directly from the IRA custodian to a
qualified charity. Unlike most IRA withdrawals, a QCD is generally not taxable
and is not added to the donor's adjusted gross income. A QCD is only available
when the donor reaches age 70 ½, and when the donor reaches the age of required
minimum distributions (RMD), the QCD goes toward the RMD amount.
A donor-advised fund, or DAF, is an account that holds charitable gifts,
often appreciated assets such as stocks or mutual funds. Donors may be eligible
for an immediate charitable deduction when contributing to the fund while
retaining the flexibility to recommend grants to charities over time.
What are the primary differences between a QCD and a donor-advised fund?
The two have more differences than similarities.
A QCD involves only IRA assets and moves money directly from the IRA to a
charity. A donor-advised fund can be funded with several types of assets, and
one contribution can support grants to charitable organizations for years.
Remember that even though the age to start RMDs has increased in recent years,
the kickoff of the QCD option begins at age 70 1/2!
Contributions to a donor-advised fund are generally tax-deductible for those
who itemize. A QCD is not claimed as a charitable deduction, but the
distributed amount is excluded from adjusted gross income (AGI). That
distinction may help some donors avoid increased Medicare premiums or the
phase-out of other popular deductions that are tied to AGI.
Why have donor-advised funds become such a popular charitable giving option?
A donor-advised fund offers flexibility.
For example, a donor may choose to make a larger charitable contribution
during a year with unusually high income and receive the associated tax
benefits at that time. The funds can then be granted to charitable
organizations over several years rather than all at once.
DAFs also make it easy to involve family members in charitable giving
decisions. Parents and grandparents can include younger generations in
conversations about philanthropy, helping create a tradition of giving that
continues for years to come.
Who might benefit from making a gift through a QCD?
A QCD may be especially useful for donors age 70½ or older. Because fewer
taxpayers itemize their deductions today, many donors do not receive an
additional tax benefit from traditional cash or even DAF gifts. A QCD can
provide a similar benefit by keeping the IRA withdrawal out of adjusted gross
income.
It can also help donors who are taking required minimum distributions.
The portion sent directly to charity through a QCD may count toward the
required distribution without being included in the donor's taxable income.
How can a QCD become part of someone's annual support for Berry?
Some
donors use a QCD to make consistent annual gifts to Berry. Even a modest
distribution can provide reliable support for students while fitting naturally
into the donor's broader financial plan.
Because the funds move directly from the
IRA to Berry, a QCD can make
annual giving straightforward and
help donors incorporate support for
students into an existing financial plan.
As both a financial planner and Berry alumnus, what inspires you about helping people give back?
What
inspires me most is helping people connect what matters to them with the causes they care
about. Berry
gave me experiences and relationships that continue to shape my life, and it is
meaningful to help others find a way to support that same opportunity for
future students. Whether the gift is made during a donor's lifetime or through
an estate plan, the right approach can turn personal values into a lasting
impact.